The Operating System
for Swiss Business.
One platform. Infrastructure and AI, built by the same team, sold to the same customer. Recurring revenue, high switching costs, category-defining — and the first customers have signed.
Two megatrends. One converging market.
Digital Sovereignty
Europe is pulling off US hyperscalers. Every Swiss business wants Swiss-owned infrastructure — and almost nobody offers a real alternative yet.
The Agentic AI Wave
Every company wants AI that does the work, not just answers questions. The winners will be the platforms with real access to the business, not another chatbot.
One platform. Two products. A single moat.
EasySystems Marketplace
Swiss-owned cloud infrastructure. The sticky, recurring-revenue foundation every customer runs their business on.
AtlasOS
The AI layer on top. You talk to it like any chat — it just doesn't stop at the answer: it then goes and does the work in the real systems. Whoever already takes the infrastructure adds it on — no new customer, no second sales process.
Not a mockup. A live system, recorded.
Every frame is a screen recording of a live Atlas OS v0.1.72 — real tasks, three different models, real output. The video itself was produced by Atlas OS.
And this is what a prospect receives.
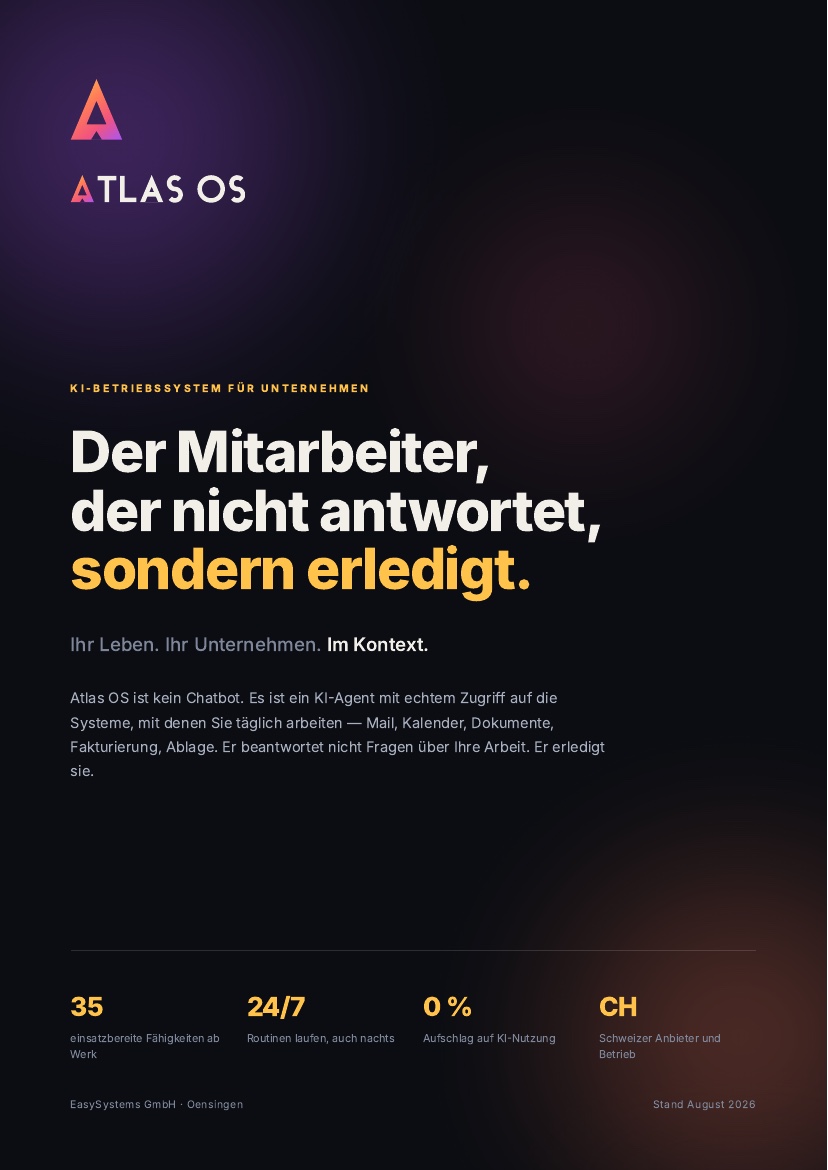
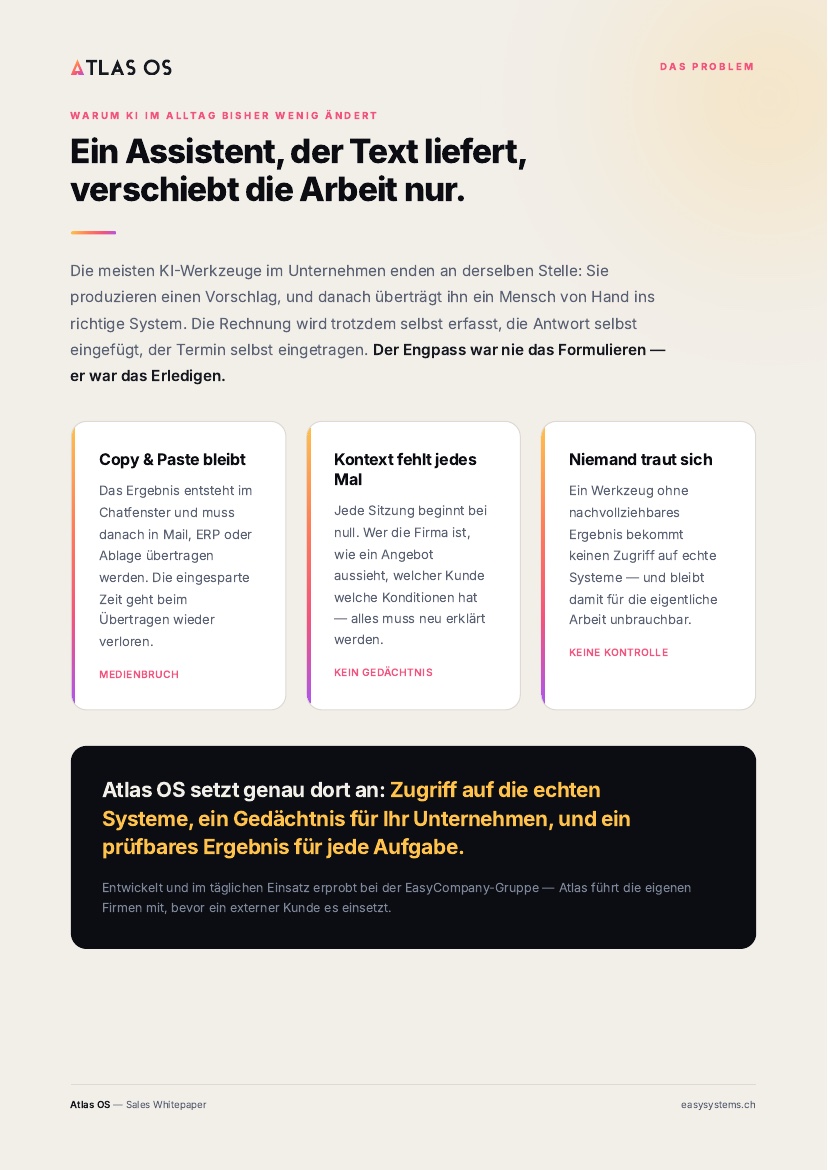
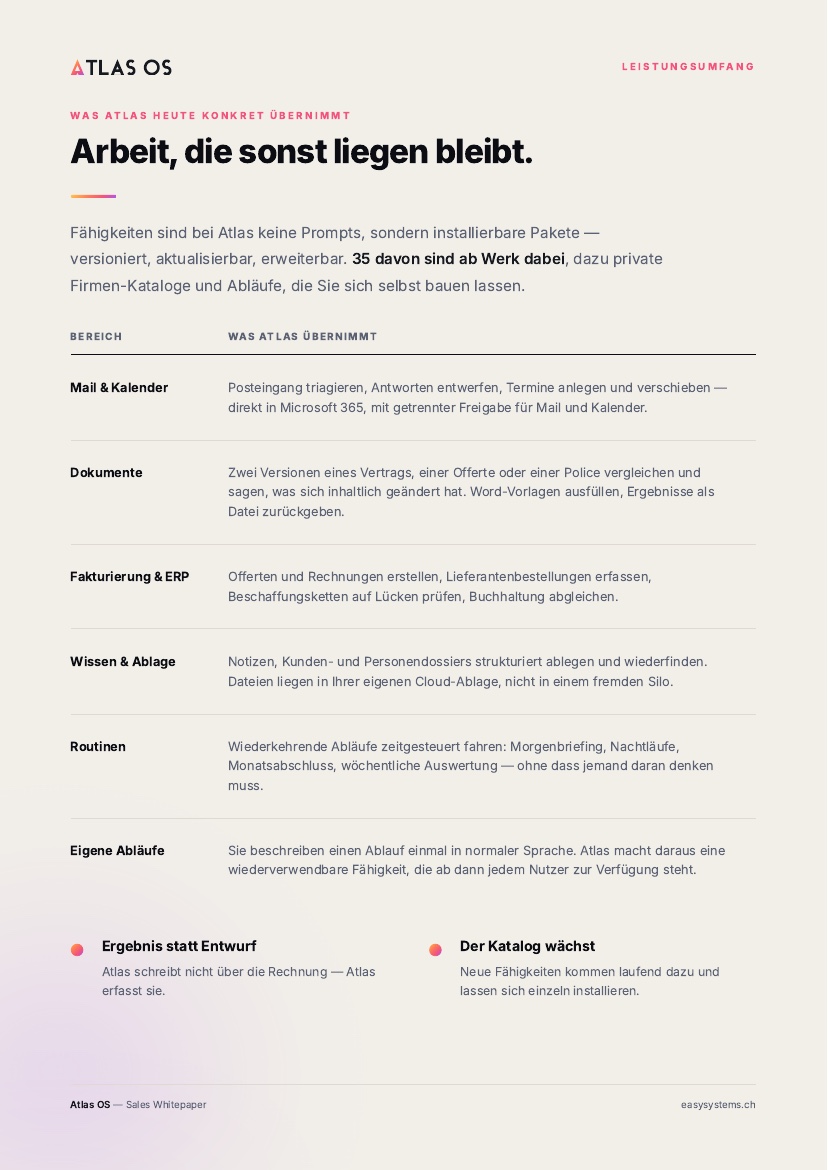
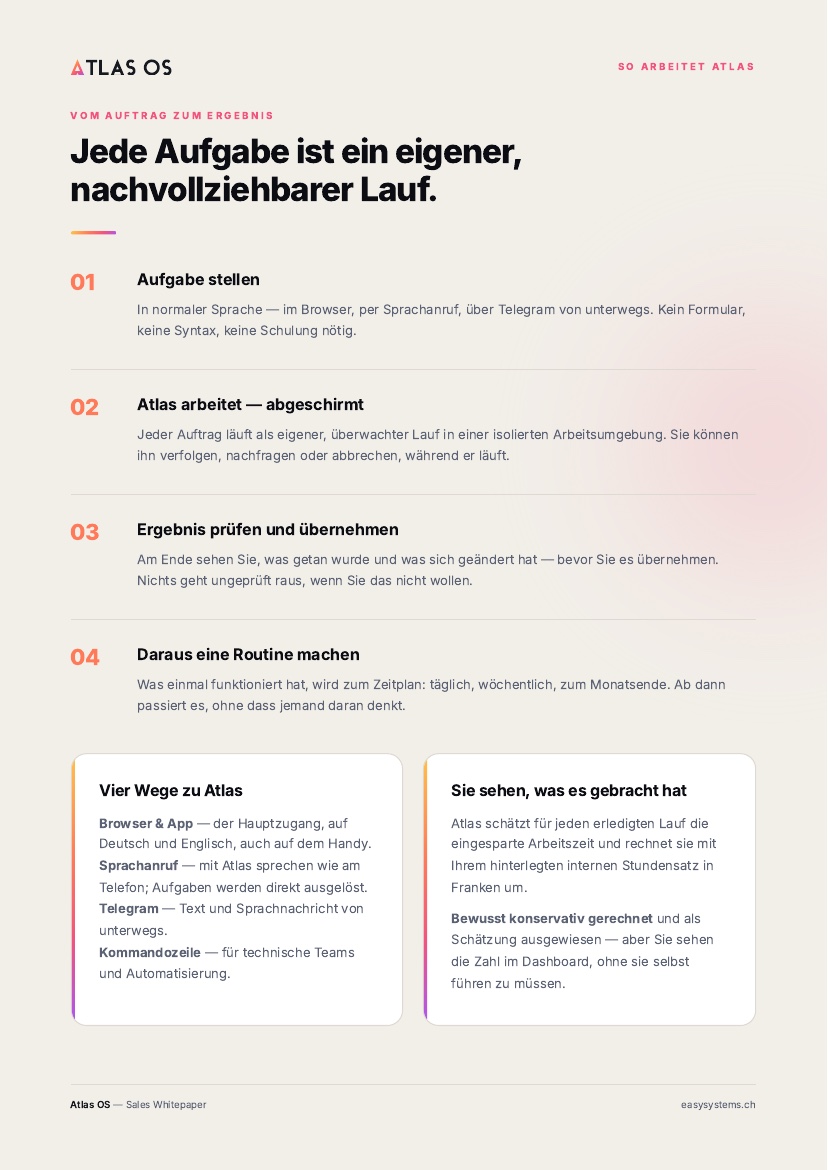
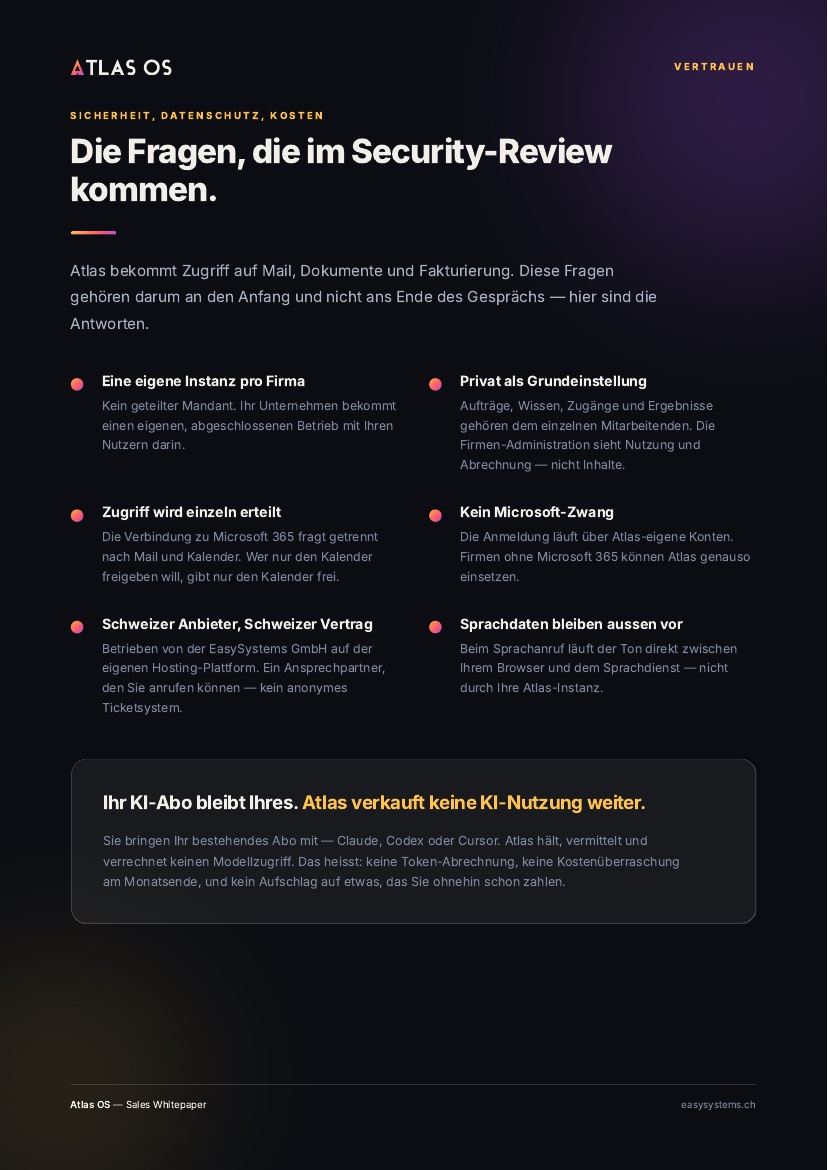
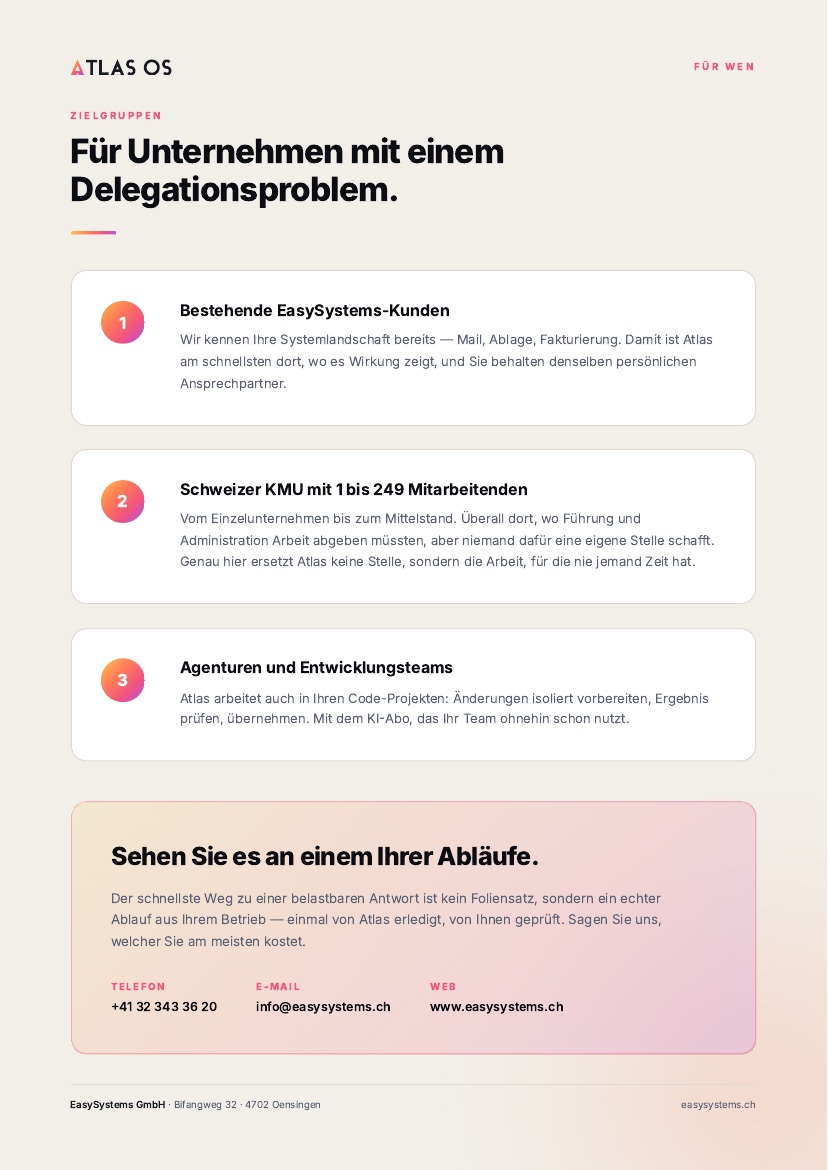
The customer-facing collateral the cold-call campaign lands on. It carries no price — the seat price is not formally released, so nothing is quoted to a customer until it is.
Built by operators who run their own business on it.
Proven Operator
Already runs a live, multi-company Swiss group on this platform — not a concept, not a prototype.
Proven in our own operations
The founder's own companies were the first paying use case — demonstrated in daily use before anything was sold externally. The first external customers have now signed.
Full-Stack Moat
Infrastructure and AI, built by one team. Nobody else is building both layers of this stack together.
CHF 63.4M ARR at 0.8% penetration of the Swiss market.
AtlasOS at CHF 200 per user / month, 5.5 seats per customer. We don't need to win the market — we need a sliver of it.
Scenario D — the base case, and the only one with a fully modelled cost structure. NPV CHF 85.4M.
Use of Funds
- Sales team & go-to-marketCHF 6.0M
- InfrastructureCHF 3.75M
- Product & engineeringCHF 3.75M
- ReserveCHF 1.5M
Bond Terms
- Ticket sizeCHF 10,000
- Coupon6.0% p.a.
- Term10 years
- Volume1,500 tickets · CHF 15M
- Closenext 2–4 months
Product valuation implied at 3.1×–4.5× ARR — see valuation benchmarks → Illustrative projections, not a forecast of actual results. Based on CHF 200/seat/month, 5.5 seats per customer, ~600,000 Swiss SMEs. Values the AtlasOS product line on its own ARR — not a valuation of the EasyCompany group, and shown before debt. Bond terms indicative and subject to final documentation.
First customers signed. The bridge takes us to market now.
The marketing launch is set for 31 August 2026 and the first customers go live mid-September. The bond places over the next 2–4 months — after both. That gap is what the bridge is for. In an undertaking like this speed decides: this market gets divided over the next months, not the next years.
Convertible Bridge Loan
- AmountCHF 250,000 – 750,000
- DenominationCHF 10,000 — same as the bond
- Coupon6.0% p.a.
- Conversioninto the bond, at placement
- Expected term2 – 4 months
What It Funds
- Onboarding the signed customersnow
- Multi-tenant productisationhosted AtlasOS
- Marketing launch & customer go-live31 Aug / mid-Sept
- Working capital to bond close2 – 4 months
What the CHF 0.9M means — and why the bond is CHF 15M. The CHF 0.9M is the
minimum: what AtlasOS needs to get through and then grow out of its own revenue from 2028. That
is the slow path — growth at the pace of your own cash flow. The bond buys speed. At
CHF 2,500 of acquisition cost per customer, CHF 15M funds roughly 6,000 additional customers directly
instead of earning them out of revenue over years. That is the difference between 0.8% and 2% penetration
on the previous slide — and in this market, first mover takes it.
Why more capital genuinely means faster here: because acquisition pays, and pays
quickly. CHF 2,500 per customer, recovered in 2.4 months, LTV/CAC around 20×. The money
is not burned, it is converted into customers who pay for themselves inside a quarter and then contribute
roughly CHF 10,400 of EBITDA a year. The constraint is therefore neither demand nor product — it is the
capital to fund marketing and sales up front. The bridge sits inside the CHF 0.9M and covers
only the weeks until placement. It converts into the bond at placement on the
same 6.0%, so it is an early subscription rather than additional debt, and the capital structure is
untouched.
The denomination deliberately matches the bond's: CHF 10,000. Every tranche then
converts without a remainder — CHF 250,000 becomes 25 bond tickets, CHF 750,000 becomes 75. A different
denomination would produce fractional tickets at conversion that have to be settled one by one. Bridge
terms are indicative and subject to documentation. The forecast on the previous slide remains fully modelled:
the first signed customers are not yet contributing observed revenue.
A 10-year bond at 6% p.a., closing over the next 2–4 months, to scale Swiss-owned infrastructure and the AI layer running on top of it — one platform, one go-to-market, two products compounding together.
What the CHF 15M is for: speed. AtlasOS gets through on CHF 0.9M and grows under its own power from 2028 — just slowly. The bond funds customer acquisition, team and infrastructure up front instead of paying for them out of cash flow over years. In a market being divided in months rather than years, that is the whole difference.
Bridge in the meantime: CHF 250,000–750,000 as a convertible loan at 6.0%, converting into the bond at placement — coming in now is subscribing to the bond early. See the previous slide.
Confidential — prepared for investor discussion only. Not an offer to sell securities.